
Weekly GTA Housing Market Brief
The Bank of Canada Hiked, Housing Got a 'Subdued' Outlook,
and Your Renewal Math Just Changed.
Sunday, November 1, 2026 · Peter Kiriazopoulos, Kompass Realty Group
2.50% Bank of Canada rate, first hike since 2023 | ~3.5% inflation the Bank sees by year-end | 4.54% avg 5-yr fixed, early October | ~54% Chow's share of the Toronto vote |
Welcome back. Here's the frame I'd use heading into the week: last Sunday the hike was the base case, and on Wednesday it became fact. The Bank of Canada raised its overnight rate a quarter point to 2.50%, its first increase since July 2023, and it left the door open to more.
The housing reaction was close to unanimous: a market that was already cautious just got a bit more expensive to finance. For buyers, sellers and homeowners with a renewal coming up in Markham, Stouffville, Richmond Hill, Vaughan, Newmarket, Scarborough and Toronto, here is what changed, what didn't, and what to do about it. We also close the loop on Toronto's election.
This Week at a Glance
Indicator | Latest | Prior / context | Read |
Bank of Canada overnight rate (Oct 28) | 2.50% | 2.25% since late 2025 | First hike since Jul 2023 |
Bank Rate / deposit rate | 2.75% / 2.45% | Moves in step | Mechanical |
Big-bank prime rate | 4.70% | 4.45% | Variable borrowers pay more |
Bank's inflation view | ~3.5% by year-end | 3.1% in September; ~3% avg in 2027 | 2% target not until mid-2028 |
Bank's growth view | 1.0% in 2026 | About 2% in 2027 and 2028 | Q4 slows on new U.S. tariffs |
Unemployment | About 6.5% | Steady for several months | Soft labour market |
CREA 2026 sales forecast | 5.2% below 2025 | Jan call was +5.1%; third cut | Forecasters reset |
Avg 5-yr fixed (early Oct) | 4.54% | 4.13% in Aug; 3.91% in Jan | Bond-driven climb |
Ontario mortgage arrears, Q2 | 0.32% | CMHC: rising through mid-2027 | Pressure building |
1. The Bank Hiked, and Told You It Might Again
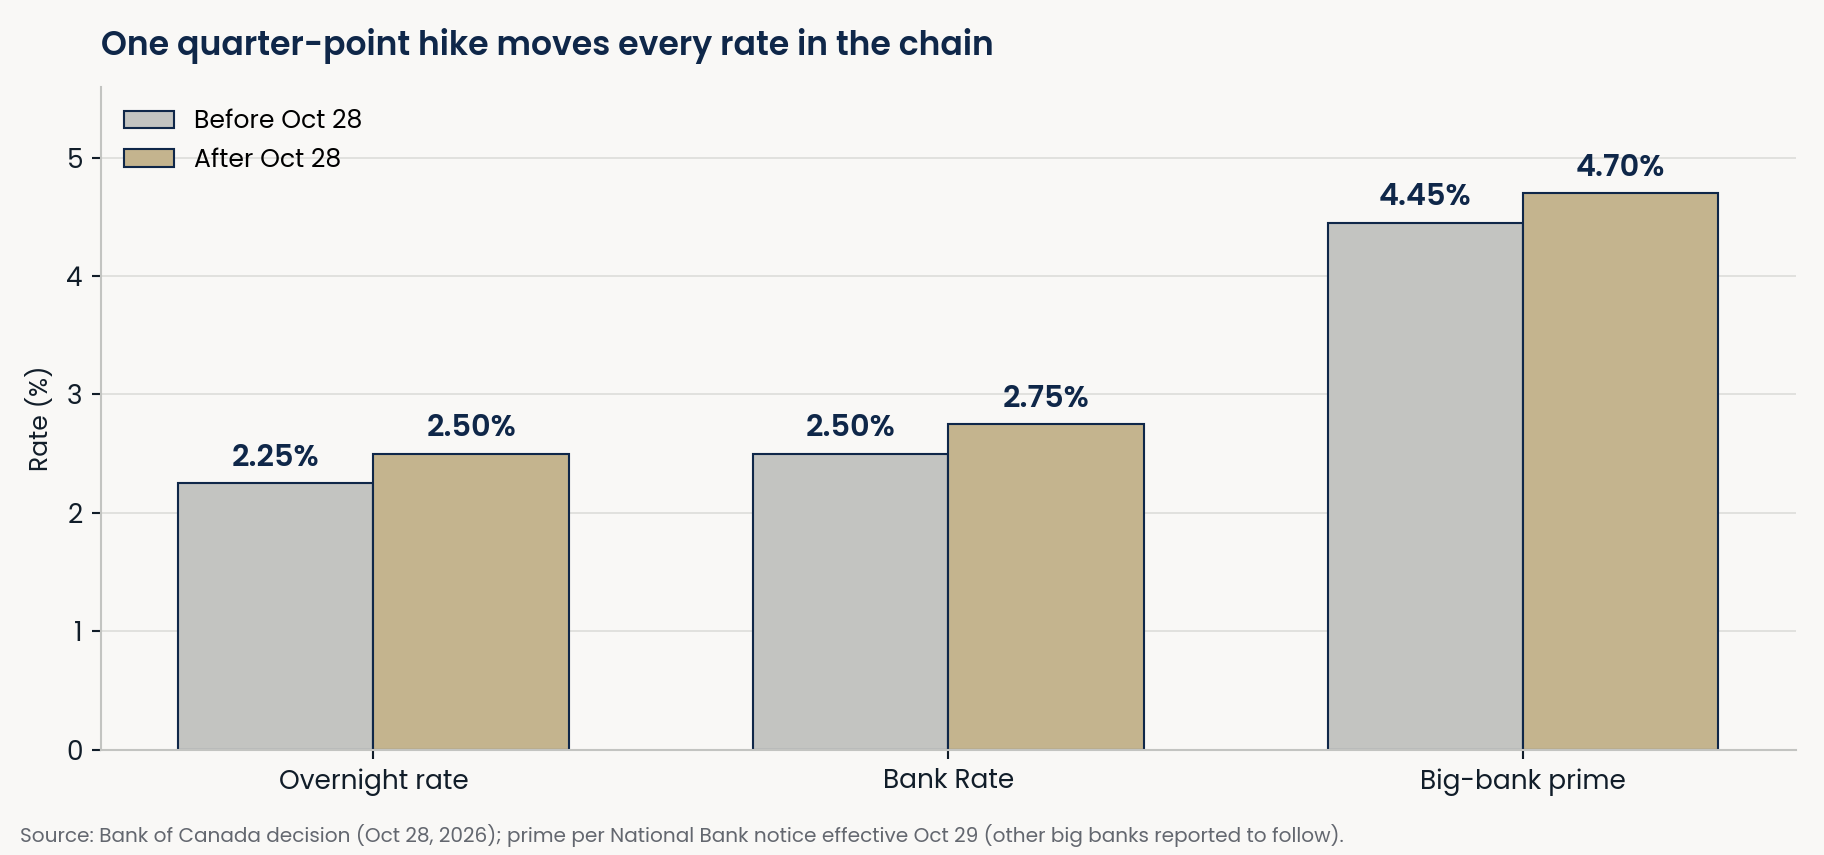
On Wednesday, October 28 the Bank of Canada lifted its overnight rate by 25 basis points to 2.50%, putting the Bank Rate at 2.75% and the deposit rate at 2.45%. The decision matched where markets and a majority of economists had landed in the final week, though plenty of forecasters had expected a hold only a month ago. The Bank's logic is about energy. With the Middle East conflict keeping oil well above what it assumed in July, it wants to stop higher fuel costs from spreading into everyday prices. Its new forecast has headline inflation near 3.5% by year-end, averaging about 3% in 2027 and not returning to 2% until around mid-2028.
The growth picture is more mixed than the inflation one. Second-quarter GDP grew 3.3% annualized, the Bank sees the third quarter around 2%, and it expects a slowdown in the fourth quarter as new U.S. tariffs bite, with 2026 growth at about 1% and a pickup to roughly 2% in 2027. Unemployment has hovered near 6.5% for months. Governor Macklem signalled that more increases are possible but that the Bank will go one meeting at a time. Bay Street is split on what that means. TD expects one more quarter-point in the first quarter of 2027, CIBC sees a December hold with a move in January, and RBC characterized this one as preventive medicine rather than the start of a cycle. The next decision is December 9.
This hike is about oil, not overheating. That is why it feels awkward for housing. |
2. Housing's Outlook: Subdued, and the Bank Says So
The Bank didn't hide from the housing consequences. Senior Deputy Governor Carolyn Rogers described the outlook for housing as subdued, said borrowing costs are already weighing on the market, and noted a hike adds to that at the margin. The Bank's report has housing subtracting about 0.1 percentage points from growth this year. It also flagged that higher energy and import costs will push up construction and maintenance costs.
The backdrop was already soft. CREA now forecasts 2026 national sales 5.2% below 2025, after starting the year calling for a 5.1% gain, its third downgrade. Ontario is where the financial strain shows most clearly, concentrated in the GTHA and southwestern Ontario as tariffs weigh on manufacturing and autos: the provincial mortgage arrears rate reached 0.32% in the second quarter, still below historical peaks, but CMHC expects it to keep rising through mid-2027. CREA's typical-home price for the Toronto region was about $918,000 in September. Brokers like Ownright's Joel Fox expect year-over-year declines in activity through the rest of 2026 and into 2027, while CMBA Ontario formally opposed the hike, arguing affordability is the immediate problem. Others, including Royal LePage, think the confidence hit will be modest. Both can be true: the market is more cautious than panicked.
3. Your Renewal Math: Variable Feels It First, Fixed Already Did
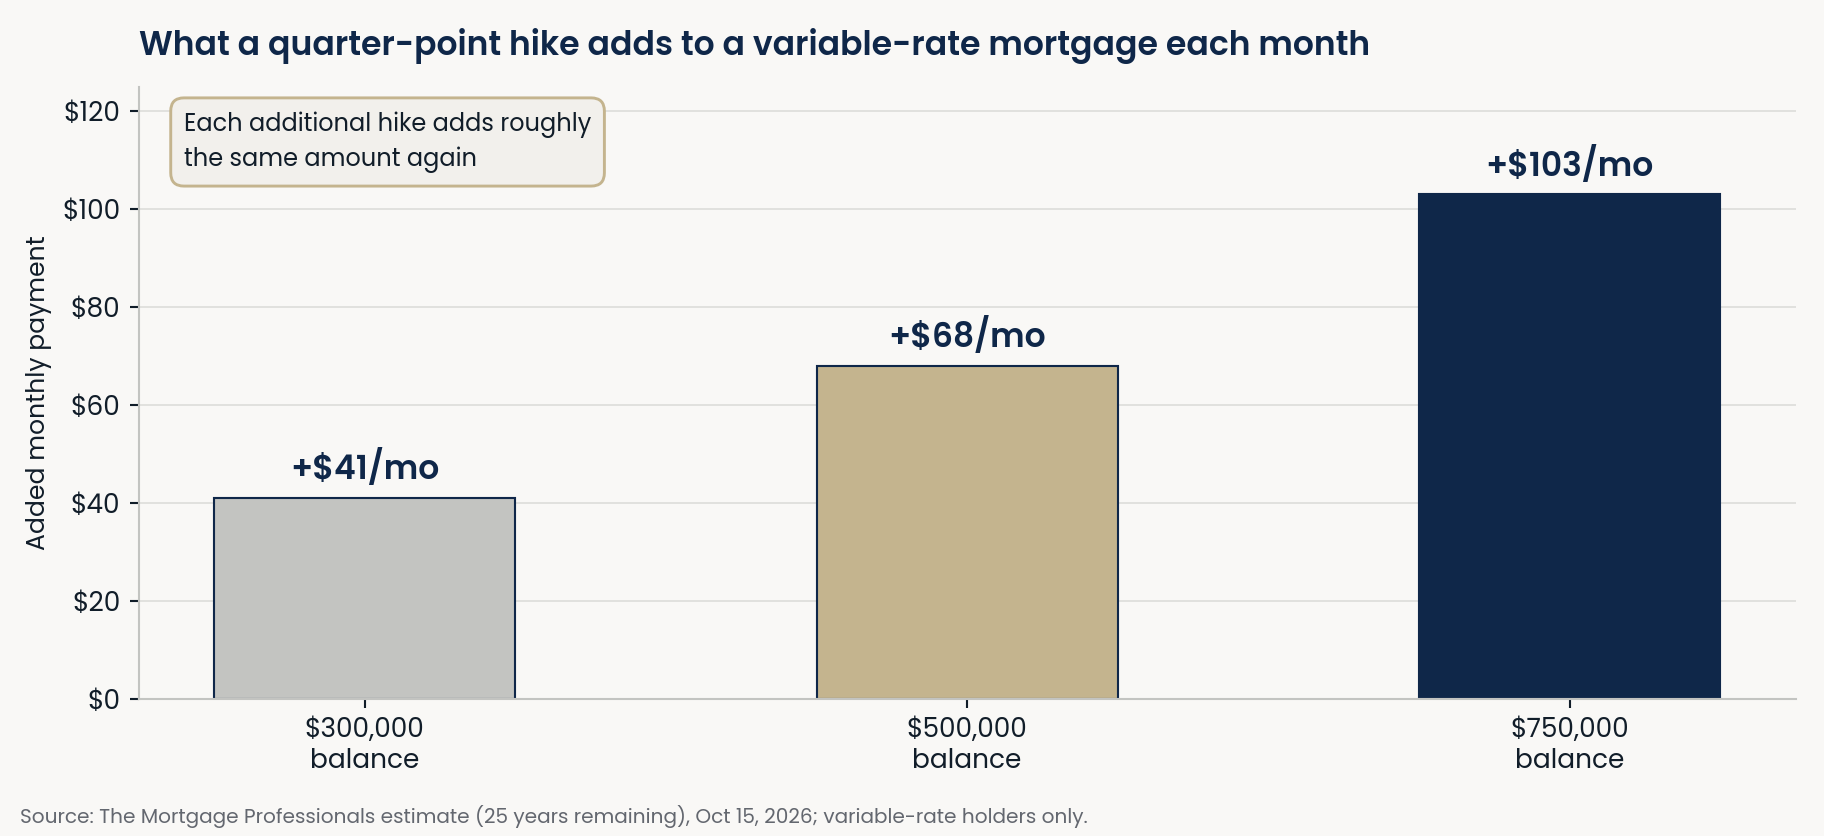
A hike passes straight through to variable-rate borrowers. National Bank confirmed a 25-basis-point increase in prime to 4.70% effective October 29, and the other big banks are reported to be following. The Mortgage Professionals estimates the cost at about $41 a month on a $300,000 balance, $68 on $500,000 and $103 on $750,000, assuming 25 years remaining. If a second hike arrives in the first quarter, roughly double it.
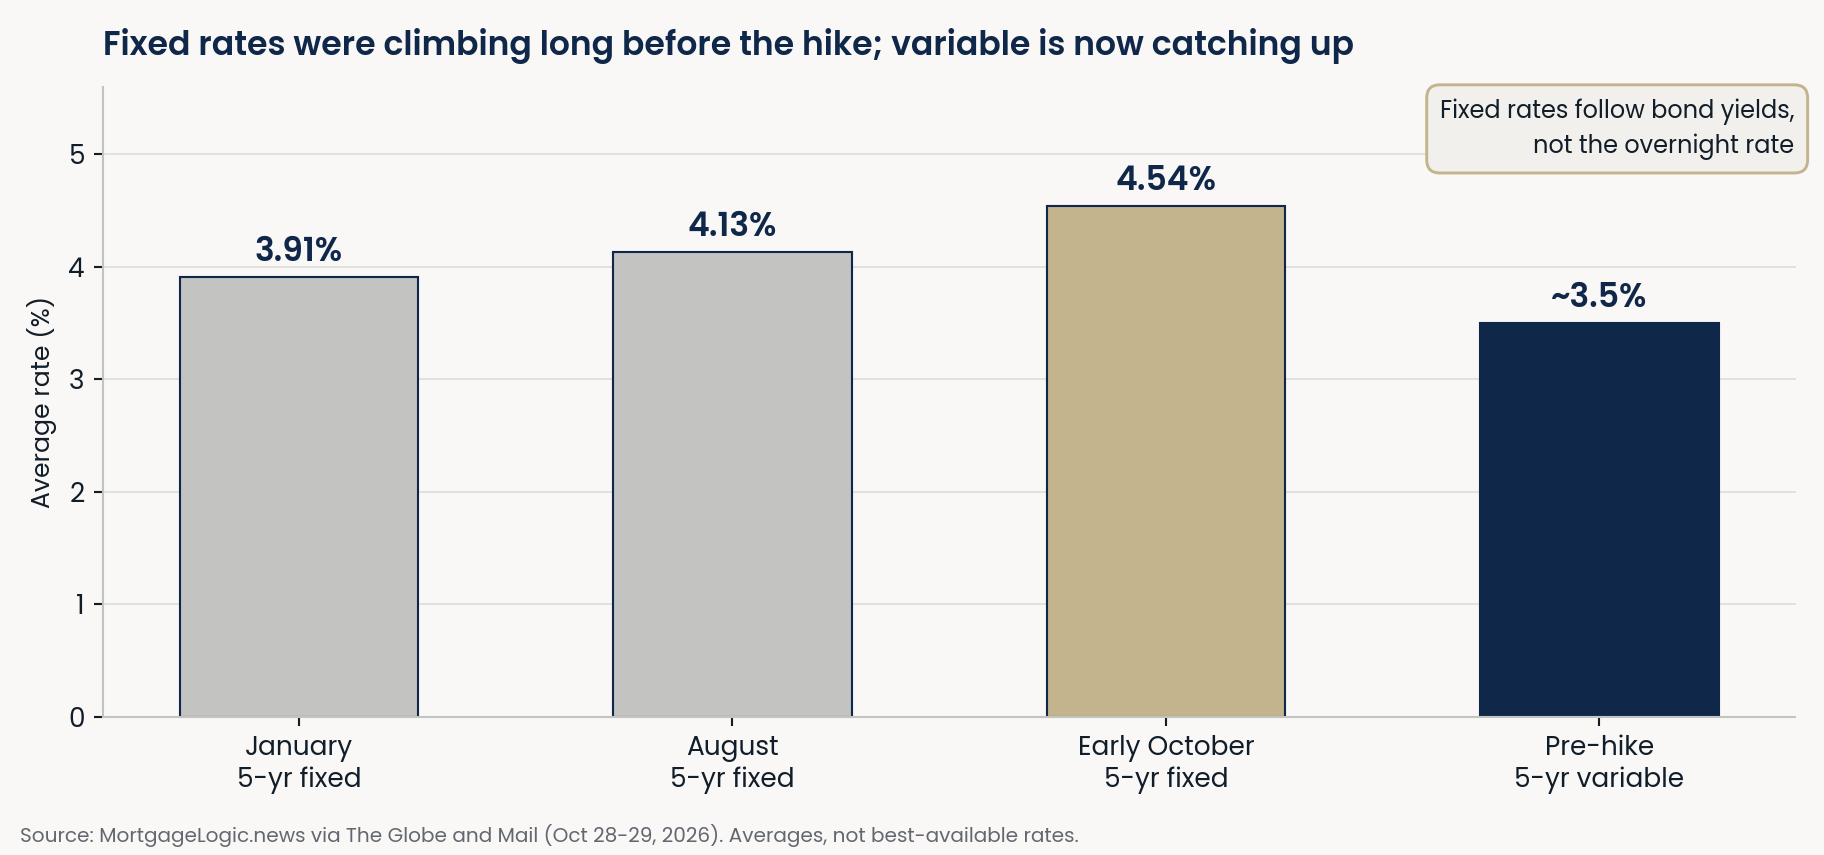
Fixed-rate borrowers are in a different spot. Fixed rates track bond yields, and the average five-year fixed was 4.54% in early October, up from 4.13% in August and 3.91% in January, according to MortgageLogic.news. Two-year bond yields barely moved after the decision, so the hike itself did little to fixed pricing, though a further rise in yields into 2027 could push costs up again. The average five-year variable was around 3.5% before the hike. That gap is why the variable-versus-fixed question is back on the table, and why the cheapest option today may not be the safest one if a second hike lands. If your renewal is within a year, start the conversation now: get a written rate hold, compare your lender's offer with a broker's, and confirm the payment before the notice arrives.
4. Toronto Re-Elects Chow, and the GTA Mayors Mostly Stay Put
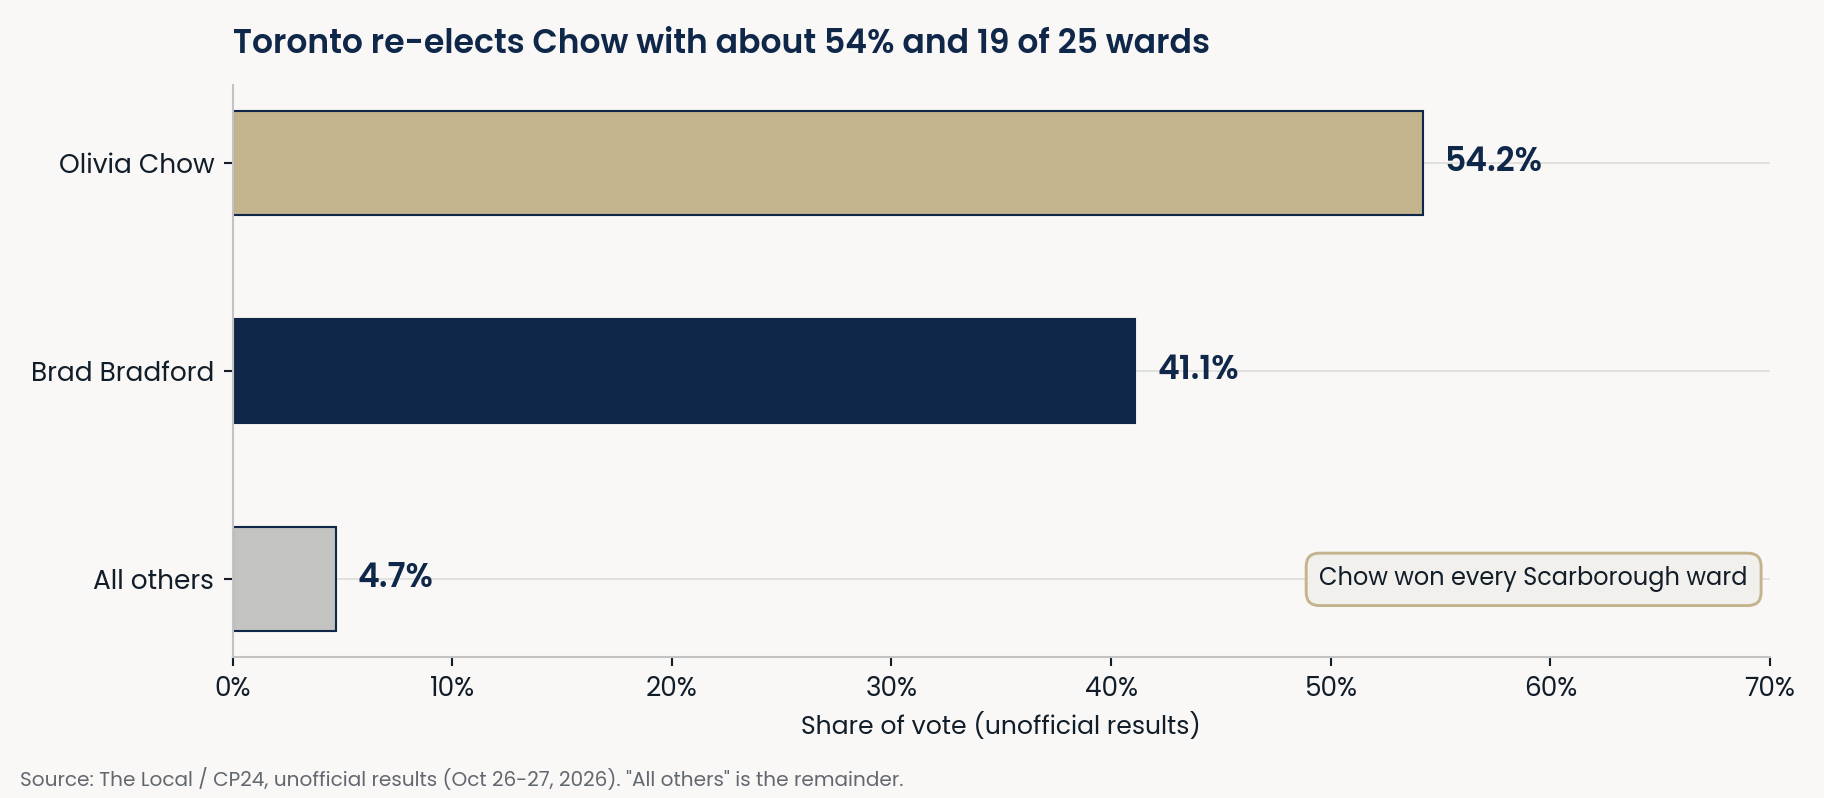
Toronto voted last Monday, and Olivia Chow won a second term over Brad Bradford with about 54% of the vote and a margin of more than 127,000 ballots, carrying 19 of 25 wards including every ward in Scarborough. Her campaign leaned on affordability. Bradford's housing platform, a first-year property tax freeze and scrapping the land transfer tax on homes under $1.1 million, did not carry the city. Several council incumbents lost, so expect a somewhat different council when housing approvals and fees come up for debate.
Elsewhere in the GTA the picture was steadier: Markham's Frank Scarpitti was re-elected with about 71%, Vaughan's Steven Del Duca took roughly 81%, and Brampton's Patrick Brown won re-election with about 55%, while Mississauga elected Alvin Tedjo over incumbent Carolyn Parrish. For buyers shopping in York Region, continuity in Markham and Vaughan means few surprises in local planning and fees. The bigger housing swing factors this winter are rates, bond yields and tariffs, not City Hall.
Peter's Take
Here's how I'm reading it. The hike is small in dollars but big in message: the Bank is willing to tighten into a soft economy, and it hasn't ruled out a second. That keeps buyers cautious and makes this a negotiation market for well-prepared people. Rates are a planning variable, not a reason to freeze.
If you're buying: qualify at a rate a half point above today's, get a written rate hold, and use the slower pace. Inventory is still sizable in many segments, so negotiating room exists on listings that have sat, even as new listings pull back.
If you're selling: price to the most recent comparable sales, not last spring's. Buyers' budgets just shrank by a small but real amount, and well-presented freehold homes in Markham, Stouffville and Richmond Hill still draw interest. Pricing right in week one matters more than usual.
If you're a homeowner renewing: don't wait for the notice. Variable holders feel the hike immediately; fixed holders should shop early because bond yields, not the Bank, set your rate.
What to watch next: TRREB's October numbers in the first week of November; the Bank of Canada's December 9 decision; CMHC's October starts; and bond yields, which will drive fixed rates. If you'd like to talk through your renewal date, your street or your price range, reach out. That conversation is always more useful than the general one.
Sources
• CP24 / BNN Bloomberg - "Bank of Canada raises interest rate as inflation projected to worsen" (October 28, 2026): cp24.com/news/canada/2026/10/28/bank-of-canada-raises-key-interest-rate-says-another-hike-possible/
• InvestingLive - Full statement from the Bank of Canada rate decision (October 28, 2026): investinglive.com/central-banks/the-full-statement-from-the-bank-of-canada-rate-decision-for-october-2026-hikes-by-25-basis-points/
• Bloomberg - "Bank of Canada Hikes to 2.5%, Says More Could Be Needed" (October 28, 2026): bloomberg.com/news/articles/2026-10-28/bank-of-canada-hikes-to-2-5-says-more-could-be-needed
• The Canadian Press via Yahoo Finance - "BoC warns of 'subdued' outlook for housing market as rate hike raises borrowing costs" (October 28, 2026): ca.finance.yahoo.com/news/boc-warns-subdued-outlook-housing-150954641.html
• The Globe and Mail (Rachelle Younglai) - Rate hike expected to slow sales in Canada's slumping housing sector (October 28-29, 2026): theglobeandmail.com/business/article-bank-of-canada-rate-hike-housing-sales/
• Mortgage Professional America - "Canada's rate hike deepens broker worry over a struggling housing market" (October 28, 2026): mpamag.com/ca/mortgage-industry/industry-trends/canadas-rate-hike-deepens-broker-worry-over-a-struggling-housing-market/595348
• The Mortgage Professionals - Bank of Canada rate decision, what it means for your mortgage (October 15, 2026): themortgageprofessionals.ca/bank-of-canada-rate-decision-october-2026/
• National Bank of Canada - prime rate increase notice (effective October 29, 2026): nbc.ca/about-us/news-media/press-release/2026/20261028-nbc-increases-prime-rate.html
• CP24 - Toronto election results: Olivia Chow re-elected as mayor (October 27, 2026): cp24.com/local/toronto/2026/10/27/chow-re-elected-in-toronto-tedjo-wins-in-mississauga-how-gta-election-night-unfolded/
• The Local - Olivia Chow is re-elected as Toronto mayor: thelocal.to/olivia-chow-re-elected-toronto-mayor/
• Rate, forecast and payment figures are as reported by the sources above; the share of the vote for "all others" is a remainder calculation. Results are unofficial pending certification.
Peter Kiriazopoulos, Sales Representative · Kompass Realty Group · RE/MAX Ultimate Realty Inc., Brokerage · 1739 Bayview Avenue, Toronto
This brief is provided for general information only and is not intended as financial, mortgage, legal or tax advice. Market data is sourced as cited above and is subject to revision. Not intended to solicit buyers or sellers currently under contract with another brokerage.