
Weekly GTA Housing Market Brief
The Cut Everyone Waited For Faded, the Economy Firmed
Instead, and the GTA Market Found a Gear.
Sunday, July 12, 2026 · Peter Kiriazopoulos, Kompass Realty Group
2.25% expected 6th straight BoC hold — Wed July 15 | +9.4% GTA June home sales, year-over-year (TRREB) | $1.06M GTA average price — decline is narrowing | ~3.94% best 5-yr fixed (variable ~3.35%) |
Welcome back. For most of the past month, the whole rate conversation hinged on one thing: the price of oil. Two weeks ago crude was collapsing, and I told you the case for a fall rate cut had quietly come back to life. Here's the frame I'd use heading into this week — the story flipped again, but in a way that actually matters more. The Bank of Canada is set to hold rates on Wednesday, and this time it isn't agonizing over oil at all. It's holding because the economy underneath finally firmed up.
That's the real headline of the week: April growth rebounded, June added jobs and pulled unemployment down again, the trade surplus hit a four-year high — and the GTA housing market posted its best month of the year. The rate cut everyone kept waiting for is fading not because the news got worse, but because it got better. Let's walk through what that means for buyers and sellers across Markham, Stouffville, Richmond Hill, Newmarket, Scarborough and Toronto.
1. Wednesday's Hold Is the Easy One — Because the Economy Firmed
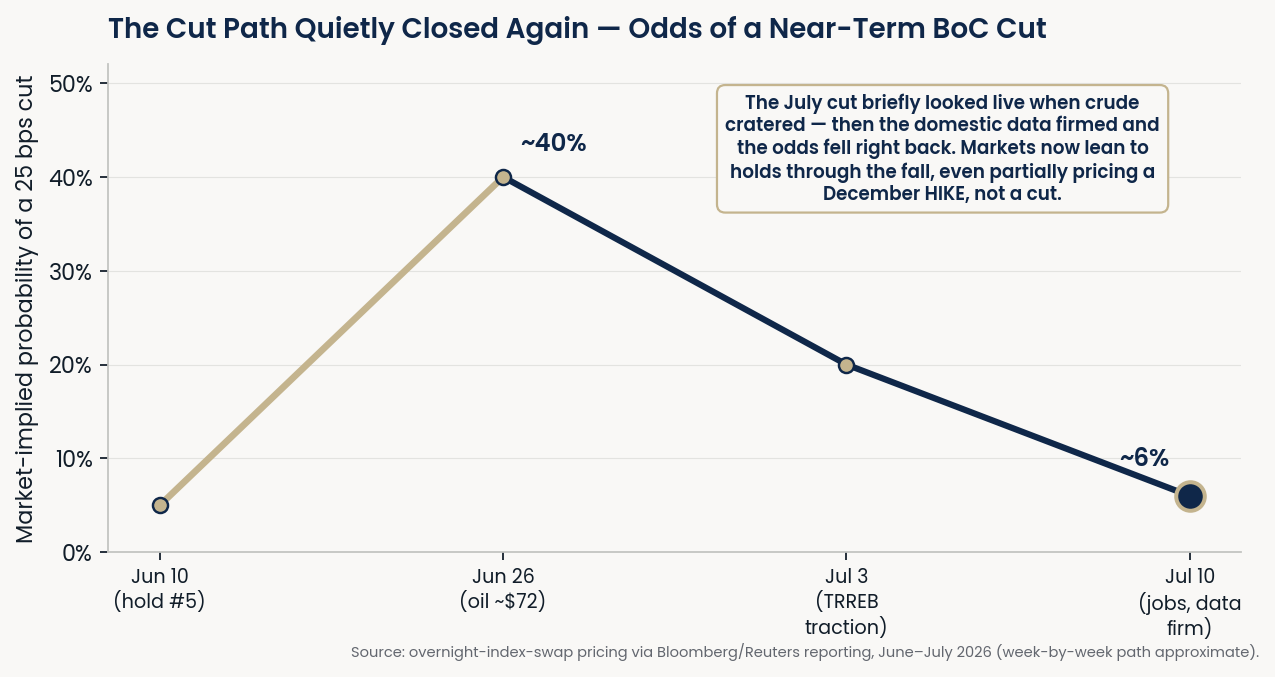
The Bank of Canada announces its next rate decision on Wednesday, July 15, and it is widely expected to hold the overnight rate at 2.25% for a sixth straight time (prime stays 4.45%). On its face that's a non-event — markets put the odds of no change around 94%. But how the Bank got here is the story. For five straight decisions, holding was a genuinely hard call: a soft economy argued for cuts, while elevated oil and a 3.2% May inflation print argued against them. This time the tension has largely resolved — and it resolved on the strong side.
Look at what landed over the past few weeks. Real GDP rebounded 0.5% in April after a soft first quarter. June added 18,000 jobs and the unemployment rate ticked down to 6.5% — its second straight monthly decline — with youth employment up 33,000 and wage growth accelerating to 3.7%. Canada's trade surplus hit a four-year high in May. And while headline inflation ran hot at 3.2% in May, that was almost entirely gasoline; the Bank's core measures have settled back near 2%. Governor Macklem's message, in effect: we're comfortable where we are, and this is about the right level to keep inflation contained.
Here's the part that catches people off guard. Two weeks ago, as oil cratered, swaps markets briefly priced the odds of a July cut near 40%. As this firmer data rolled in, those odds collapsed right back toward single digits — and the market has quietly shifted to pricing holds through the fall, with a modest chance of a December HIKE, not a cut. My read: don't hold your breath for cheaper money in 2026. The friendlier interpretation is the better one — rates are steady because the economy is healthier than the doom-scrollers feared, and a steady 2.25% is a perfectly workable backdrop to buy or sell into.
2. Oil Whipsawed Back — But It Stopped Being the Deciding Factor
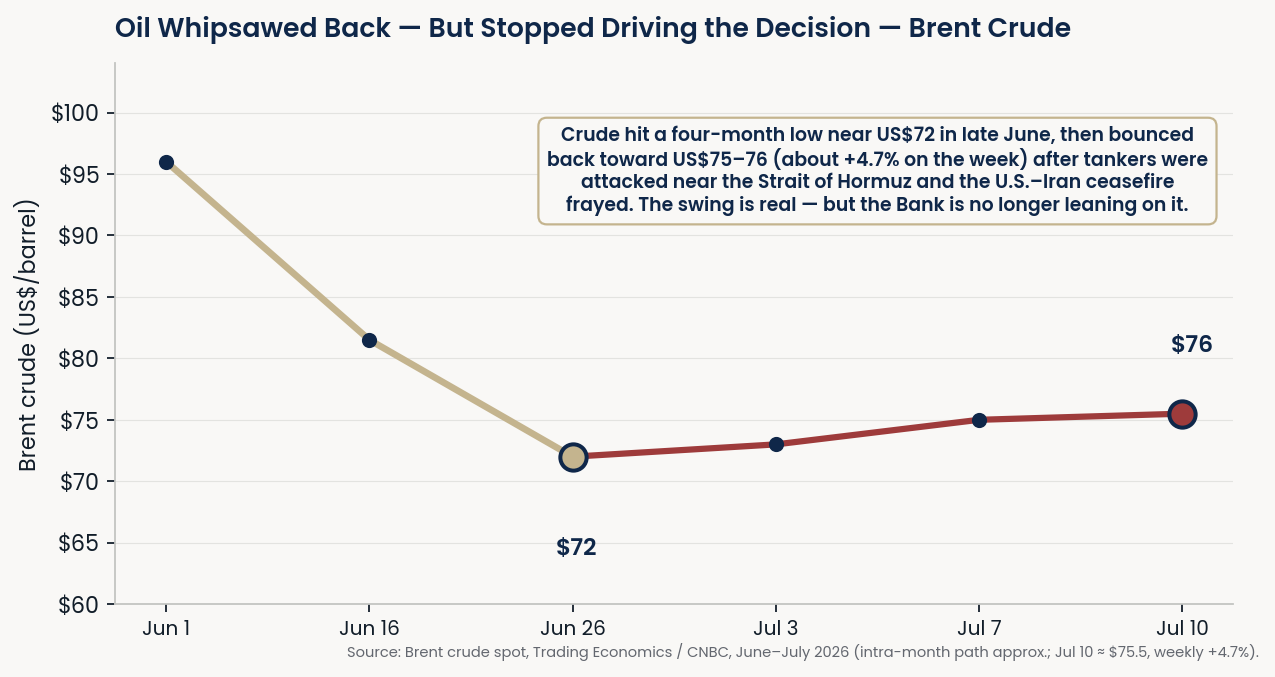
Remember the four-month low? Just two weeks after Brent crude cratered to about US$72 a barrel on hopes of a U.S.–Iran deal to reopen the Strait of Hormuz, the trade reversed. Three vessels were attacked in or near the strait on Tuesday, the U.S. revoked an authorization for Iran to sell oil, and President Trump signalled the ceasefire was effectively over. Brent climbed back toward US$75–76 by Friday — a gain of roughly 4.7% on the week — as the war-risk premium snapped back into the price.
A month ago, that kind of swing would have dominated this letter, because oil was the single variable the Bank of Canada was leaning on. The quietly important shift this week is that it isn't anymore. With April growth, June jobs and the trade surplus all pointing the same direction, the domestic data has taken the wheel back from the oil headlines. Crude can round-trip on a single geopolitical rumour; the labour market and GDP don't. That's a healthier place for the rate outlook to sit.
What it means at the mortgage desk: not much movement, and that's fine. The menu still sits where it has — the best 5-year fixed is hovering around 3.94% (insured), with the Big Six closer to the high-4s, while the best variable is near 3.35% and prime is 4.45%. With a fall cut now off the table, the old logic reasserts itself: if you value certainty, a fixed near 4% is a defensible number to lock; if you can carry the risk, variable still starts lower. Either way, with roughly 1.15 million Canadian mortgages renewing this year, anyone with a renewal landing in the back half of 2026 should model both paths now rather than default to whatever their lender offers first.
3. The GTA Found a Gear — June Sales Jumped 9.4%
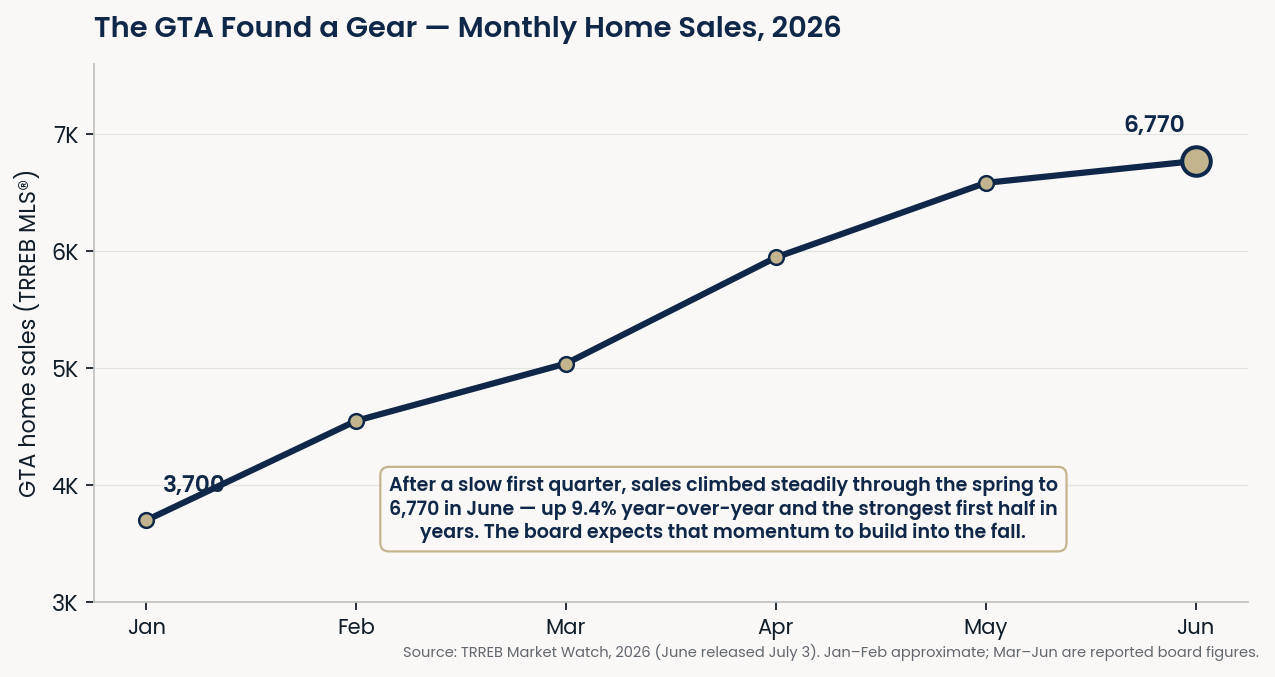
Now the part my clients actually feel. The board's June numbers, released July 3, were the strongest signal yet that the GTA has shifted out of neutral. GTA REALTORS® reported 6,770 sales in June — up 9.4% year-over-year — while new listings fell 12.9% and active listings sat 13.5% below last year. The average selling price was $1,058,658. Yes, that's still down 3.9% from a year ago — but the year-over-year decline has been shrinking for months, and on a month-over-month, seasonally adjusted basis both the average price and the MLS® Home Price Index actually rose versus May. The rear-view mirror is still red; the windshield is green.
Trace the year and you can see the market find its footing: sales climbed from a sluggish winter through a genuinely strong spring, and the first half of 2026 outpaced the first half of last year across the board. The board's own read — and I'd frame it the same way the analysts I follow, John Pasalis and Daniel Foch among them, have been framing it — is that demand is building against a shrinking supply of fresh listings, which is the setup that eventually turns into price growth. TRREB is now openly forecasting accelerating transactions and renewed price gains in the back half of the year.
I'll keep it honest, though: this is a firming market, not a runaway one, and active inventory is still elevated compared with the frenzied years — there's a real backlog of homes out there, so buyers keep genuine choice. Where the traction is clearest is exactly where I spend my time: York Region freehold. Vaughan, Markham and Richmond Hill led York's activity in June, and detached and townhome demand across Markham, Stouffville, Richmond Hill and Newmarket continues to firm — with City of Toronto detached still averaging around $1.65M and the GTA-wide detached figure near $1.36M. The buyer-friendly window hasn't slammed shut, but the direction of travel is unmistakable.
4. The Condo Twist: Resale Sales Are Waking Up
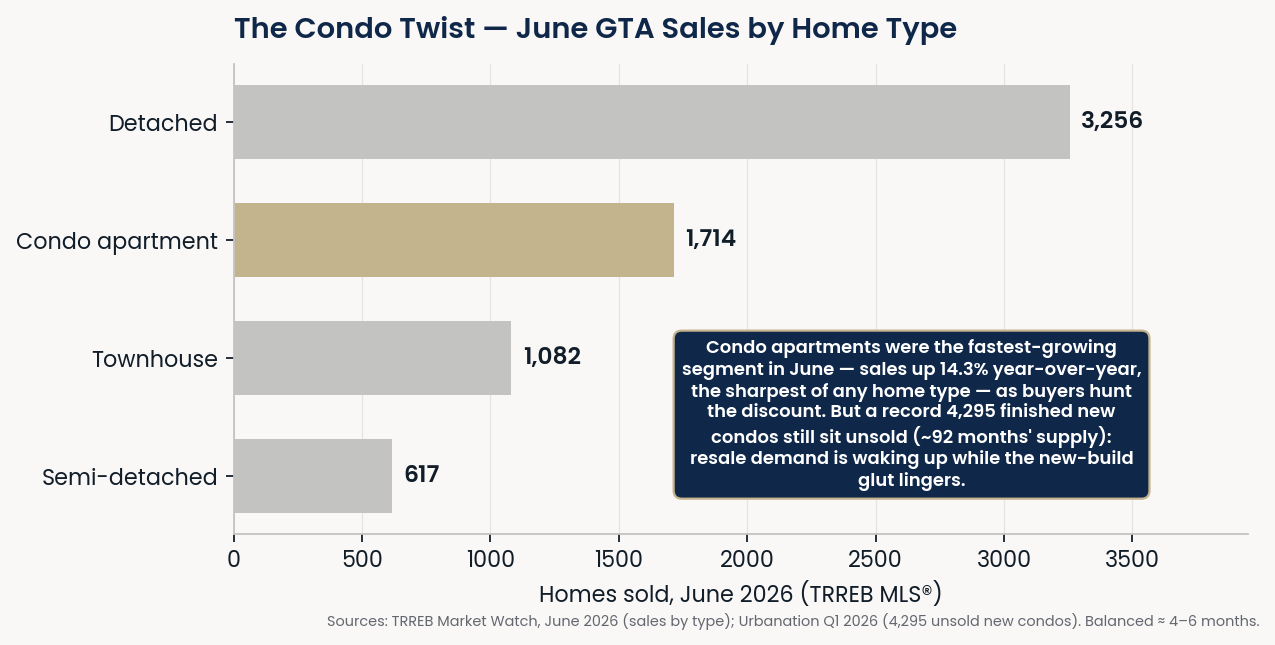
Here's the plot twist in this week's data. For a year I've described the condo segment as stuck on a different, much slower clock than freehold — and the standing-inventory side of that is still true. But look at the sales line: condo apartments were the fastest-growing segment in June, with sales up 14.3% year-over-year — the sharpest gain of any home type. That's 1,714 condos sold at an average of $630,688 and a median of $540,000. After a brutal two years, buyers are finally stepping back in to hunt the discount.
Don't mistake that for an all-clear on the new-build side, though — the two clocks are still very different. A record 4,295 newly completed condos sat unsold as of the first quarter — roughly 92 months of standing supply at the current pace, versus four to six in a balanced market. There were zero new project launches in Q1, the first time in decades, and unsold units still under construction hit a nine-year high. Benchmark resale prices are down about 10% year-over-year and roughly 25% from the 2022 peak, and new-build asking prices still sit a record ~38% above resale. The flagship distress story — The One at Yonge and Bloor, in receivership on well over $1.5B of debt — hasn't gone anywhere.
So the honest read is a two-part one. Resale condo demand is genuinely reviving — Urbanation now believes sales volumes have bottomed — even as the new-build overhang keeps a lid on prices and will take a couple more years to clear. One helper on the horizon: the new one-year full HST rebate on qualifying new homes is expected to knock roughly $100,000 off unsold new-condo prices and narrow that new-versus-resale gap toward 20%. For a patient buyer in downtown Toronto or Scarborough, this is still the most negotiable corner of the whole market — but the window where sales were falling has clearly turned.
Peter's Take
If you're buying
Adjust your expectations on rates, but not in a scary way. The fall cut you may have been waiting for has faded, so stop timing your purchase to a rate that probably isn't coming in 2026 — a steady 2.25% policy rate, a best fixed near 4% and a variable near 3.35% is the backdrop, and it's a workable one. Meanwhile the freehold market you're shopping in is firming: sales up, fresh listings drawing down, prices grinding higher within the year across Markham, Richmond Hill, Stouffville and Newmarket. There's still real choice out there, so no need to panic-buy — but the ‘just wait for lower prices and lower rates’ bet is quietly getting weaker on the freehold side. And resale condos in downtown Toronto and Scarborough remain the standout value play — real negotiating room, and demand there is just starting to turn. Get pre-approved on both fixed and variable, and lean on the last 30 days of comps.
If you're selling
Momentum is finally on your side — most of all in the freehold lane. A well-prepared detached or townhome in York Region is meeting the firmest demand in over a year, with fewer fresh rivals coming to market than earlier this spring; price it to meet the market on day one and you can ride that. If you're selling a condo, the news is genuinely better than it was — buyers are back and sales are up double digits — but you're still competing with discounted new supply, so sharp pricing and standout presentation are what convert that renewed traffic into a firm deal. In both lanes, days on market is still the number to beat.
If you're investing
Let the two-speed market be your map — but note that the slower speed just sped up a little. Freehold across the 905 remains the sturdier long-hold thesis: land, scarcity and end-user demand, with supply now tightening. Pre-construction condos are still broken on cash flow and appraisal risk, and the new-build glut will take years to clear. But resale condos in the 416 and Scarborough at today's reset prices — with sales now rising and the HST rebate reshaping the new-build competition — can finally pencil for a patient landlord with a real down payment. Cap rates, not capital gains. Run the actual numbers before you commit.
The bottom line this week: the rate cut everyone was waiting for faded — but for the right reason. The economy firmed, the Bank can hold on strength instead of holding its breath over oil, and the GTA market answered with its best month of the year. Pair a steady rate backdrop with a freehold market that's found a gear and a condo market where buyers are finally coming back, and the second half of 2026 is shaping up with real opportunity on both sides of the split. Two markers to watch next: the Bank of Canada decision and statement this Wednesday, July 15, and the June inflation report a week later. The clients who win this market will be the ones who know which of the two speeds they're actually standing in — and stop waiting for a rescue that the data says isn't coming.
— Peter
Sources
• The Globe and Mail — “Bank of Canada expected to hold as monetary policy dilemma fades” (July 2026 preview; hold at 2.25%, April GDP +0.5%, unemployment 6.5%, trade surplus four-year high) — https://www.theglobeandmail.com/business/article-bank-of-canada-preview-july-2026/
• Bank of Canada — Policy interest rate & schedule (decision Wednesday, July 15, 2026; prime 4.45%) — https://www.bankofcanada.ca/core-functions/monetary-policy/key-interest-rate/
• Statistics Canada — “Labour Force Survey, June 2026” (+18,000 jobs; unemployment 6.5%; youth +33,000; wages +3.7%) — https://www150.statcan.gc.ca/n1/daily-quotidien/260710/dq260710a-eng.htm
• BNN Bloomberg — “Unemployment rate falls to 6.5% in June as youth add 33,000 jobs”, July 10, 2026 — https://www.bnnbloomberg.ca/business/economics/2026/07/10/unemployment-rate-falls-to-65-in-june-as-youth-add-33000-jobs-statcan/
• CNBC — “Oil prices rise after attacks on tankers in Strait of Hormuz, U.S. revokes Iran sale authorization”, July 7, 2026 — https://www.cnbc.com/2026/07/07/oil-prices-iran-strait-hormuz.html
• CNBC — “Oil prices today: Brent, WTI rise as U.S. targets Iran” (Brent ~$75.5, +4.7% on the week), July 8, 2026 — https://www.cnbc.com/2026/07/08/oil-prices-brent-wti-iran-us-hormuz.html
• Trading Economics — Brent crude oil spot price, June–July 2026 — https://tradingeconomics.com/commodity/brent-crude-oil
• TRREB — “Market Gains Traction with Strong Home Sales in June and First Half of the Year” (June 2026: 6,770 sales +9.4%, avg $1,058,658, new listings −12.9%) — https://trreb.ca/market-gains-traction-with-strong-home-sales-in-june-and-first-half-of-the-year/
• Zoocasa — “TRREB June Sales Jump 9.4%. Is the GTA Market Finally Turning?” (sales-by-type detail; condo apts +14.3%, 1,714 sales, avg $630,688) — https://www.zoocasa.com/blog/trreb-june-2026/
• CP24 — “Greater Toronto home sales up 9.4% in June as board predicts price growth could come”, July 3, 2026 — https://www.cp24.com/news/money/2026/07/03/greater-toronto-home-sales-up-94-in-june-as-board-predicts-price-growth-could-come/
• Ratehub — Best 5-year fixed & variable mortgage rates, July 2026 (best fixed ~3.94%, variable ~3.3–3.45%) — https://www.ratehub.ca/best-mortgage-rates
• Move Smartly (John Pasalis) — Toronto real estate data & monthly market commentary, July 2026 — https://www.movesmartly.com/articles
• Daniel Foch — GTA housing market analysis & commentary, July 2026 — https://www.danielfoch.com/
• Urbanation — “Standing Condo Inventory Hits Record High in Q1” (4,295 unsold new condos; ~92 months' supply; record 38% new-vs-resale gap; sales volumes seen bottoming) — https://www.urbanation.ca/news/standing-condo-inventory-hits-record-high-q1
• Canadian Mortgage Professional — “Toronto’s condo market hits rock bottom as unsold units pile up”, 2026 — https://www.mpamag.com/ca/mortgage-industry/market-updates/torontos-condo-market-hits-rock-bottom-as-unsold-units-pile-up/572743
• TD Economics — “GTA Resale Condo Market Outlook: A Long Correction with Stabilization on the Horizon”, 2026 — https://economics.td.com/ca-gta-condo-market-outlook
Peter Kiriazopoulos*, Sales Representative · Kompass Realty Group
RE/MAX Ultimate Realty Inc., Brokerage — Independently Owned and Operated
1739 Bayview Avenue, Toronto, ON · 416-721-2298 · [email protected] · kompassrealtygroup.ca
*Personal Real Estate Corporation. Not intended to solicit buyers or sellers currently under contract. This brief is general market commentary, not financial advice.